
When we think about financial planning, we often focus on saving money, investing for the future, buying a home, or building a retirement corpus. While all of these are important, there is one financial resource that often receives much less attention despite being the foundation of many financial goals: your savings.
Your savings help you manage everyday expenses, repay loans, support your family, and invest towards long-term goals. But an unexpected illness, accident, major expense, or other life event can put your savings under pressure. When that happens, the financial impact can extend far beyond the immediate expense.
This is where savings protection becomes an important part of financial planning. The objective is not simply to build savings, but to ensure that an unexpected event does not completely disrupt the financial stability you have worked hard to build.
Why Are Your Savings Worth Protecting?
For most individuals, their savings are one of their most important financial resources. Over time, the money you save may help fund everything from your family’s daily needs to your children’s education, home purchase, retirement, and other personal goals.
However, savings can quickly come under pressure when unexpected expenses arise. If a major financial need occurs without sufficient reserves or protection in place, you may find yourself relying heavily on savings or investments to meet expenses that were not part of your original plan.
This can create a chain reaction. Money that was intended for long-term investments may have to be withdrawn to meet immediate needs, ongoing investments may have to be reduced or stopped, and additional debt may become necessary to manage expenses. Over time, an unexpected financial setback can therefore affect not only your present financial stability but also your future financial goals.
What Can Put Your Savings At Risk?
Savings can be affected by several unexpected situations, and not all of them are easy to anticipate. A serious illness or accident could result in significant medical expenses, while an unexpected financial setback could make it difficult to manage regular household commitments.
Major life events and family circumstances can also create unexpected financial pressure. A situation that requires additional spending or financial support may reduce the savings available for your other goals while simultaneously increasing your expenses.
The purpose of savings protection planning is not to predict exactly which situation will occur. Instead, it is about creating enough financial resilience to help you manage different possibilities without immediately compromising your long-term financial plans.
Build An Emergency Fund
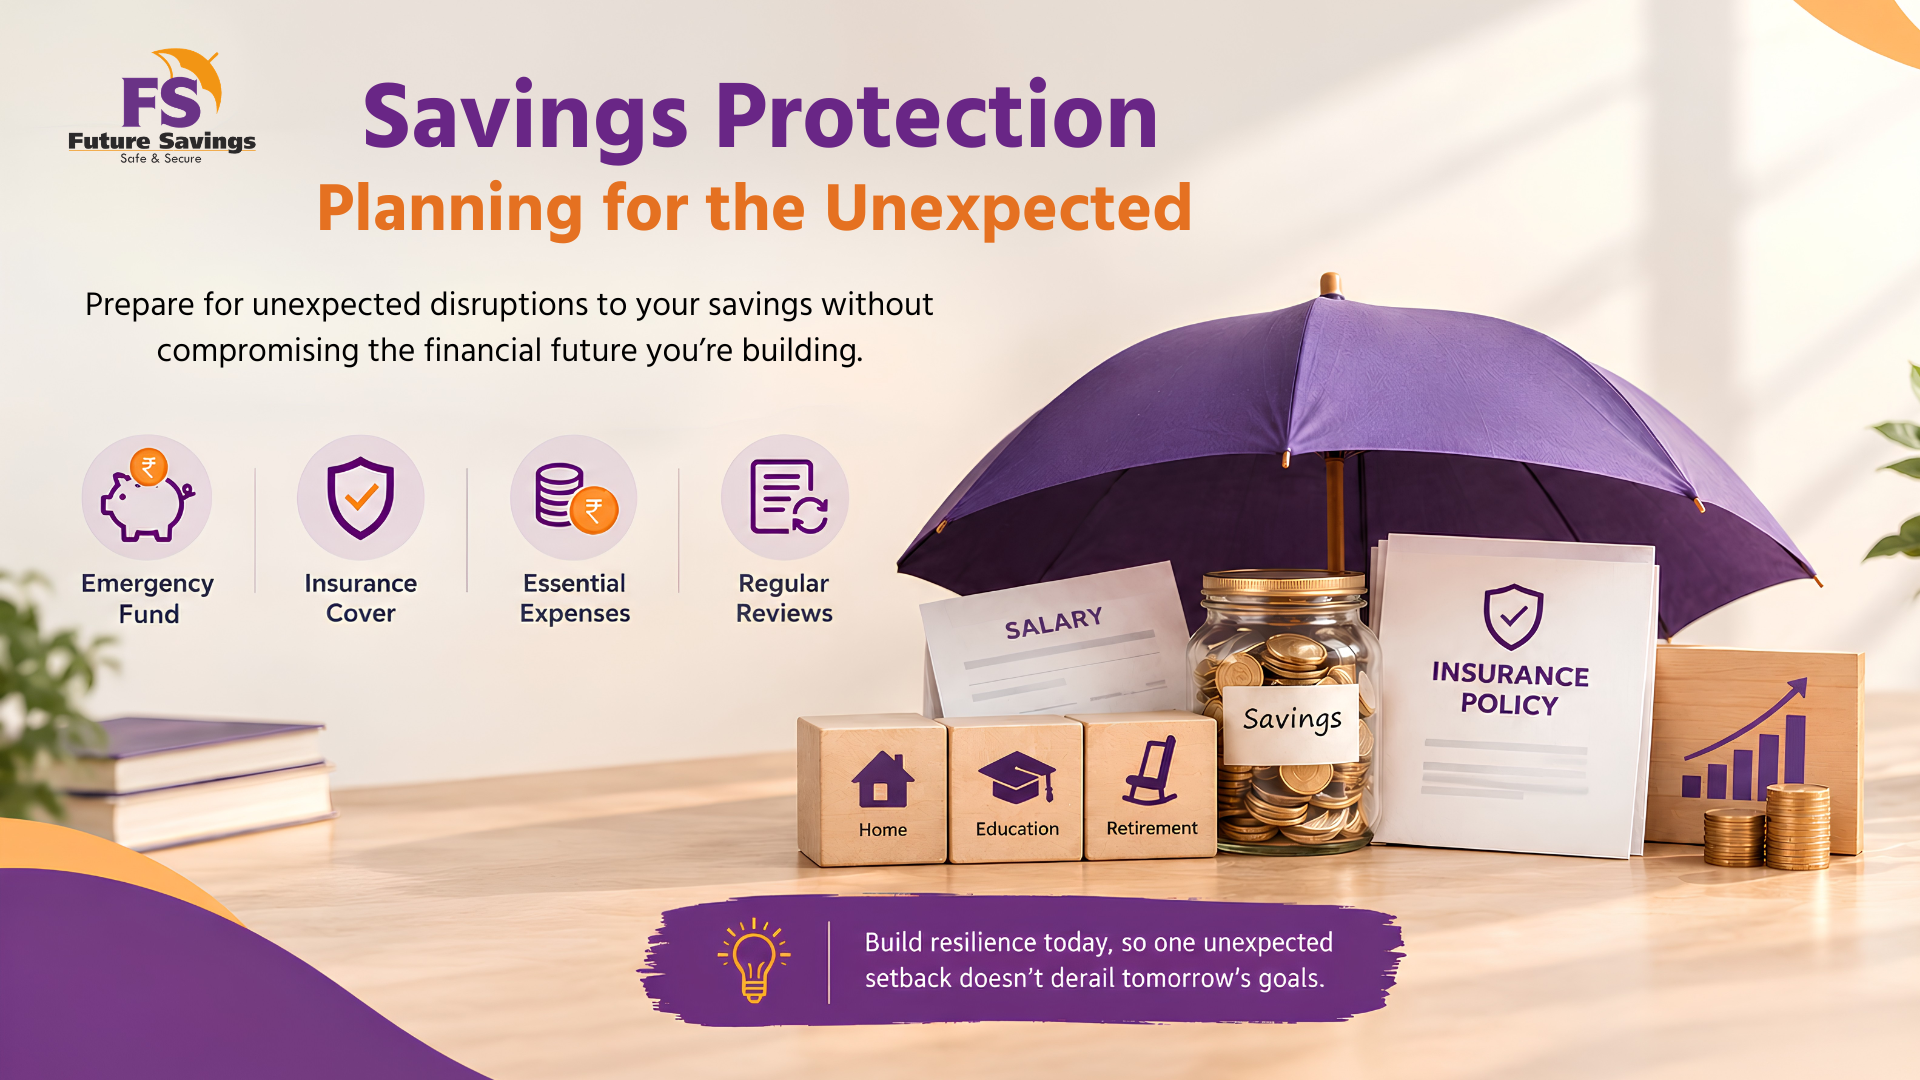
One of the simplest and most important components of savings protection is maintaining an adequate emergency fund. Savings set aside specifically for emergencies can provide a financial cushion when an unexpected expense arises.
An emergency fund can help cover essential expenses such as household costs, loan payments, utilities, insurance premiums, and other necessary commitments while you deal with an unexpected situation.
The important point is to keep this money readily accessible and separate from investments intended for long-term goals. Your emergency savings are not primarily meant to generate high returns; their purpose is to provide liquidity and financial stability when you need it most.
Review Your Insurance Protection
Savings alone may not always be sufficient when an unexpected event has a significant financial impact. This is why insurance can play an important role in a broader savings protection strategy.
Life insurance can provide financial support to your family in the event of your death, helping them manage ongoing expenses and financial commitments. Health insurance can help manage the cost of medical treatment, while other forms of insurance may provide protection against specific risks depending on your circumstances.
The right level and type of coverage will differ from person to person. Your income, age, financial responsibilities, existing assets, liabilities, family situation, and long-term goals should all be considered when reviewing your insurance needs.
Understand Your Monthly Financial Commitments
Savings protection planning should begin with a clear understanding of how much money your household actually needs to function each month.
Start by identifying your essential expenses, including housing costs, groceries, utilities, education expenses, loan EMIs, insurance premiums, and other unavoidable commitments. Once these expenses are identified, you can better understand how much financial support would be required if an unexpected expense puts pressure on your savings.
It is also important to distinguish between essential and discretionary spending. During a financial emergency, knowing which expenses can be reduced or postponed can make it easier to manage available resources without immediately using money set aside for long-term goals.
Protect Your Long-Term Investments
One of the biggest benefits of savings protection planning is that it can help prevent an unexpected event from forcing you to compromise investments that were created for the future.
For example, imagine that you have been regularly investing towards retirement or your child’s education. If an unexpected expense arises and you do not have sufficient financial reserves, you may be forced to withdraw those investments to meet immediate household expenses.
This may provide short-term relief, but it can also reduce the amount available for your original goal and potentially give your investments less time to grow. Having an emergency fund and appropriate insurance protection can therefore help create a buffer between an unexpected financial setback and your long-term investments.
Consider the Risks of Relying on a Limited Financial Reserve
For some individuals, financial security may depend heavily on a limited amount of savings or a single pool of money. While there is nothing inherently wrong with having one primary savings reserve, understanding this dependency is important when assessing financial risk.
Where appropriate, maintaining separate financial reserves for different purposes can provide another layer of financial resilience. These could include emergency savings, short-term savings, and investments for long-term goals. However, financial diversification should be approached carefully and should not involve taking unnecessary risks simply to increase returns.
The goal is to build financial resilience while keeping your overall financial strategy aligned with your risk tolerance and long-term objectives.
Revisit Your Savings Protection Plan as Your Life Changes
Your financial responsibilities are unlikely to remain the same throughout your life. As your income increases, your expenses may also grow. You may take on a home loan, get married, have children, start a business, or take on additional responsibilities for family members.
Each of these changes can affect the amount of financial protection you may need.
For this reason, savings protection should not be treated as a one-time exercise. Your emergency savings, insurance coverage, liabilities, investments, and financial goals should be reviewed periodically to make sure they continue to reflect your current circumstances.
A financial protection plan that was appropriate several years ago may no longer provide adequate support after significant changes in your income, expenses, or responsibilities.
Savings Protection Is Part of Building Financial Resilience
Financial planning is not only about achieving higher returns or accumulating wealth. It is equally about ensuring that the wealth you build and the goals you set are protected from unexpected disruptions.
When you have adequate emergency savings, appropriate insurance coverage, manageable financial commitments, and a well-structured investment plan, you create multiple layers of protection around your finances.
This does not eliminate financial uncertainty, but it can make unexpected situations easier to manage and reduce the possibility of one setback affecting every other part of your financial plan.
The Bottom Line
You cannot always predict when an unexpected financial challenge may arise, but you can prepare for the financial consequences of an unexpected disruption.
Savings protection is ultimately about protecting the financial progress you have worked hard to build. It helps you prepare for today’s uncertainties while continuing to work towards tomorrow’s goals.
A strong financial plan should therefore do more than focus on growing your wealth. It should also make sure that your family, your savings, your investments, and your long-term goals have a layer of protection when life does not go according to plan.
Because building financial security is not just about preparing for the future — it is also about protecting yourself from the unexpected along the way.